 Jira & Confluence

 Bitrix24
Pag-IBIG MP2 · 5 years · dividends
Put your ipon to work — Pag-IBIG MP2 calculator and payroll deduction letter
Short answer. The letter to your HR is open below: monthly MP2 savings straight from payroll. Who can save: All active Pag-IBIG I members regardless of income; former members and pensioners with another source of monthly income and at least 24 monthly savings (MP2 Terms and Conditions, item 1).
- MP2 matures — 5 years from the first payment: type the date
- If not withdrawn: Pag-IBIG I rates end, the savings become accounts payable (2 years after maturity): type the date
Check your own case.
Term: five (5) years reckoned from the date of the initial payment (MP2 Terms and Conditions, item 7). After maturity, unclaimed savings earn Pag-IBIG I rates for the next two (2) years, then are reclassified as accounts payable (item 9).
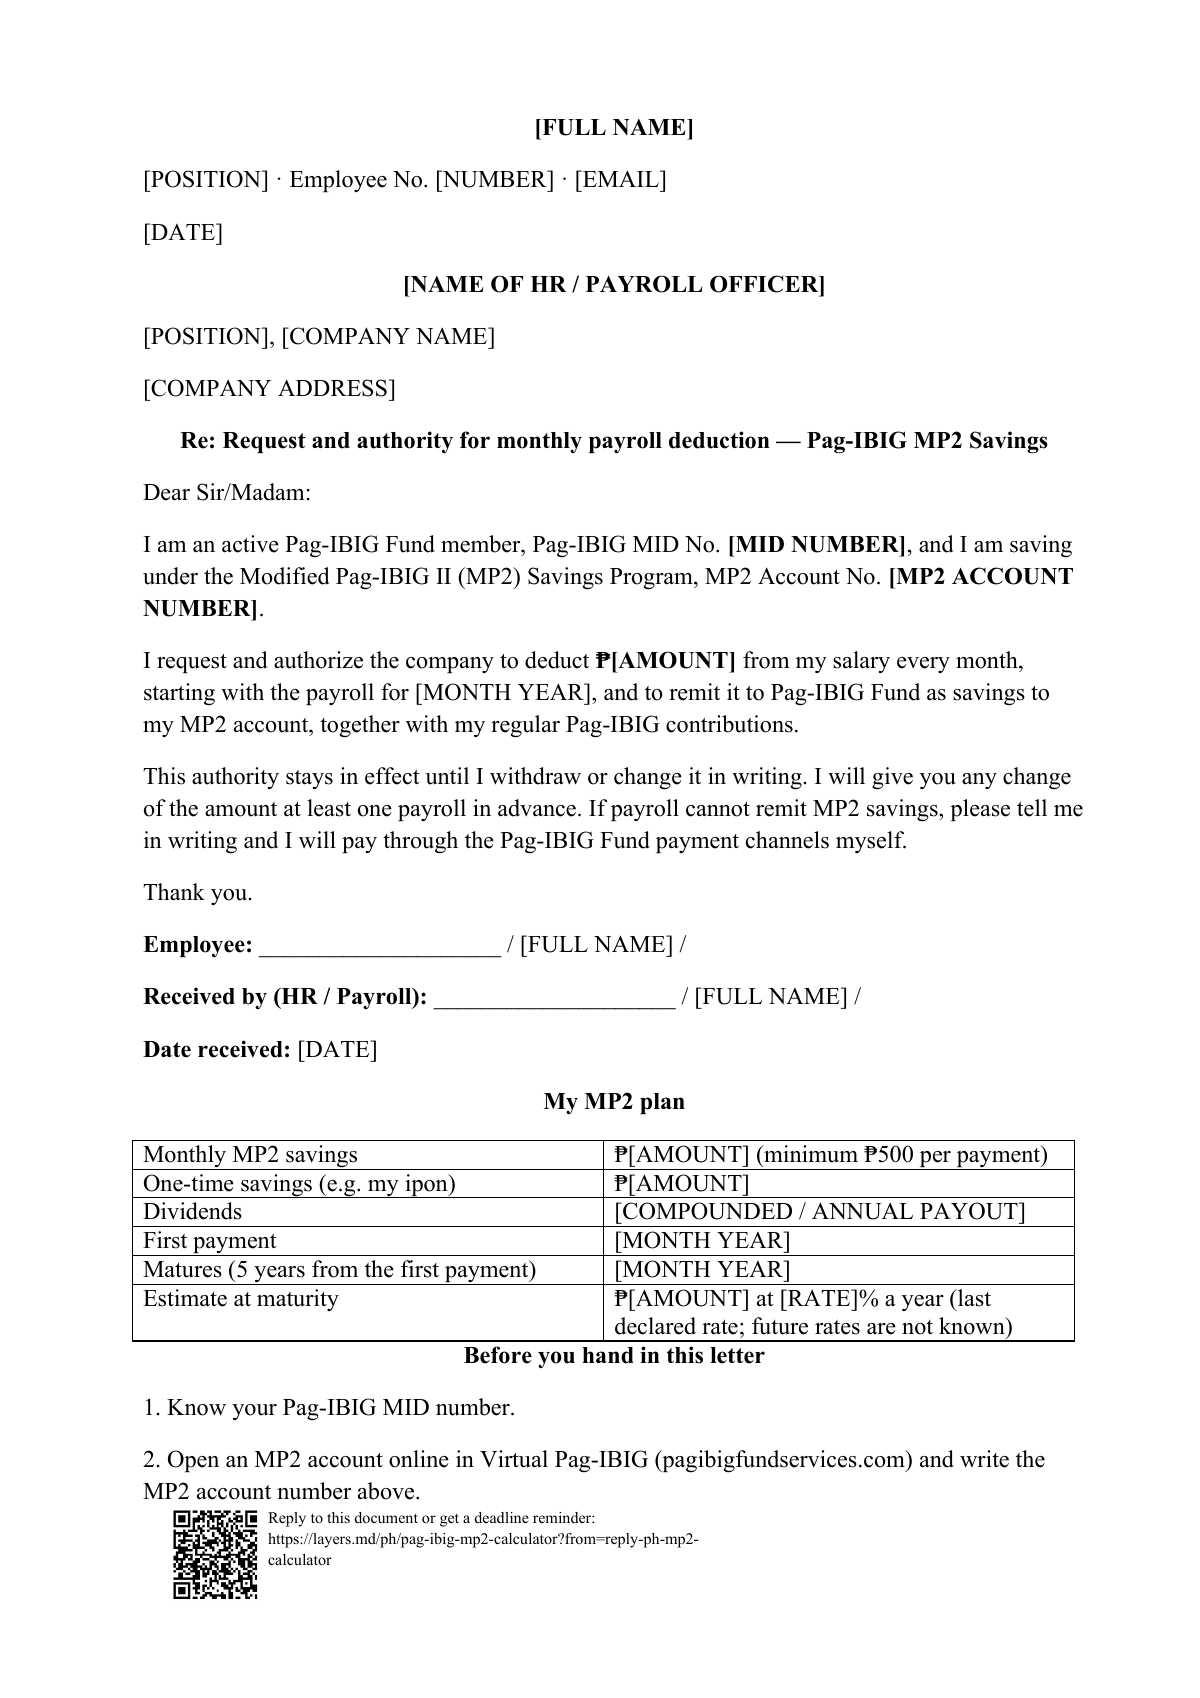
Start typing right in the document — no sign-up. It stays in this browser; save it to your free Layers account to keep it, open it on your phone and share it.
Your numbers
MP2 in 5 years — what you put in and what it grows to
Monthly savings, a one-time amount (your ipon) and how dividends come. Estimate at the last declared MP2 rate — 7.12% for 2025; change it if you want to see a lower one.
- Open your MP2 account online in Virtual Pag-IBIG and write the MP2 account number into the letter.
- Hand the letter to HR and get "Received by" signed — or pay MP2 yourself every month.
- Check that every payment appears in your MP2 records. The reminder fires before maturity: withdraw or open a new MP2.
Rules (Virtual Pag-IBIG — MP2 Savings, Terms and Conditions): minimum ₱500 per payment (item 3); dividends declared every year after the net income is approved — annual payout or compounded (items 5–6); term 5 years from the first payment (item 7); early withdrawal only for listed reasons, otherwise 50% of the dividends (items 10–11). Estimate: one rate for all years, monthly accrual, credited at each year-end; 7.12% is the rate declared for 2025 (Pag-IBIG Fund, 27 February 2026).
Atty. Liza, Layers template assistant
Tell me how much you can set aside a month, and your ipon if you have one. I will show the 5 years year by year.
Compounded grows more; annual payout gives you cash every year. The chart shows both if you switch.
An illustrated character, not a lawyer.
Deadlines
The rules, with the source
| What | Deadline | Source |
|---|---|---|
| Who can save | All active Pag-IBIG I members regardless of income; former members and pensioners with another source of monthly income and at least 24 monthly savings | MP2 Terms and Conditions, item 1 |
| Minimum | ₱500 per payment; above ₱100,000 — proof of income or source of funds; one-time savings above ₱500,000 — by personal or manager’s check | Items 3–4 |
| Dividends | Declared every year after the Board approves the net income; you choose annual payout or compounded | Items 5–6 |
| Last declared rate | 7.12% for 2025 (6.62% for regular Pag-IBIG savings), announced on 27 February 2026; 7.10% for 2024 | Pag-IBIG Fund announcement, reported by the Philippine News Agency (PNA) |
| Term | 5 years from the first payment; to continue, open a new MP2 account | Items 7, 9 |
| Early withdrawal | Allowed for listed reasons (disability, death in the family, retirement, permanent departure, layoff or closure, critical illness, OFW repatriation); otherwise 50% of the dividends is lost | Items 10–11 |
The calculator is an estimate: it applies one rate to all 5 years, accrues monthly and credits dividends at each year-end. Pag-IBIG declares each year’s rate after the year closes, so your real dividends will differ.
Step by step
What to do, in order
1
Know your MID number
Your Pag-IBIG membership ID.
2
Open an MP2 account
Online in Virtual Pag-IBIG; note the MP2 account number.
3
Choose how dividends come
Compounded (added to the balance) or paid out every year.
4
Hand the letter to HR
Monthly deduction from payroll; get "Received by" signed.
5
Put in your ipon
A one-time payment from your 52-week challenge — enter it in the calculator.
6
Check your records
Make sure every deduction appears in your MP2 account; the reminder below fires before maturity.
Questions
Is MP2 guaranteed?
The MP2 Terms say dividends are declared each year from Pag-IBIG Fund’s net income, so the rate is not fixed. The calculator uses the last declared rate, 7.12% for 2025.
Can I withdraw before 5 years?
Only for the reasons listed in the MP2 Terms (for example disability, retirement, layoff, critical illness). For any other reason you lose 50% of the dividends.
Does my employer have to deduct MP2 from my salary?
The letter is a request. If payroll cannot do it, you can pay MP2 yourself through Pag-IBIG Fund’s payment channels.
Official sources
Step 2 of 2
From ipon to dividends: the 2 steps
- 1 Save 52 weeks (ipon challenge)
- 2 Put your ipon to work (MP2)
Other documents
- 13th month pay not paid
- Want your promotion this year?
- Barangay complaint
- Certificate of Employment request letter
- Cost of rice production per hectare
- Final pay not released?
- 30 day glow up challenge
- How to start a salon business
- Invitation letter for a Japan visa
- Invitation letter for a Korea visa
- Ipon challenge 2026
- Online lending harassment
- Paluwagan template
- Quit smoking calculator
- Reply to a Notice to Explain
- Salary increase request letter
- Skincare routine chart
- Travel budget template
- ₱60 wage increase not in your payslip?
- Weight loss tracker printable
Keep the papers in one place
Letters, receipts and notices in one folder you can share with family or a lawyer. The templates and the editor are free; Layers is free for up to 20 people.
This is a ready letter and an estimate, not financial advice.