 Jira & Confluence

 Bitrix24
Online lending apps · Data Privacy Act · SEC MC 18-2019
Online lending harassment — notice ready, 15 days to the NPC counted
Short answer. The written notice to the loan app is already open below: list what the collectors did and send it to their Data Protection Officer. Written notice to the company first: Inform the lender (its DPO) in writing; the NPC acts if there is no appropriate action or no reply within 15 calendar days from receipt (NPC 2021 Rules of Procedure as amended, Rule II, s.2).
- If they do not act or reply by this date, you may file a complaint with the NPC (15 calendar days): type the date
Check your own case.
NPC Rules of Procedure (2021, as amended in 2024), Rule II, Section 2: a complaint is given due course when the complainant informed the company in writing and it did not take timely or appropriate action, or did not respond within fifteen (15) calendar days from receipt. Count from the day the company received your notice — keep the e-mail acknowledgment or registry receipt. The NPC may waive this step for serious violations.
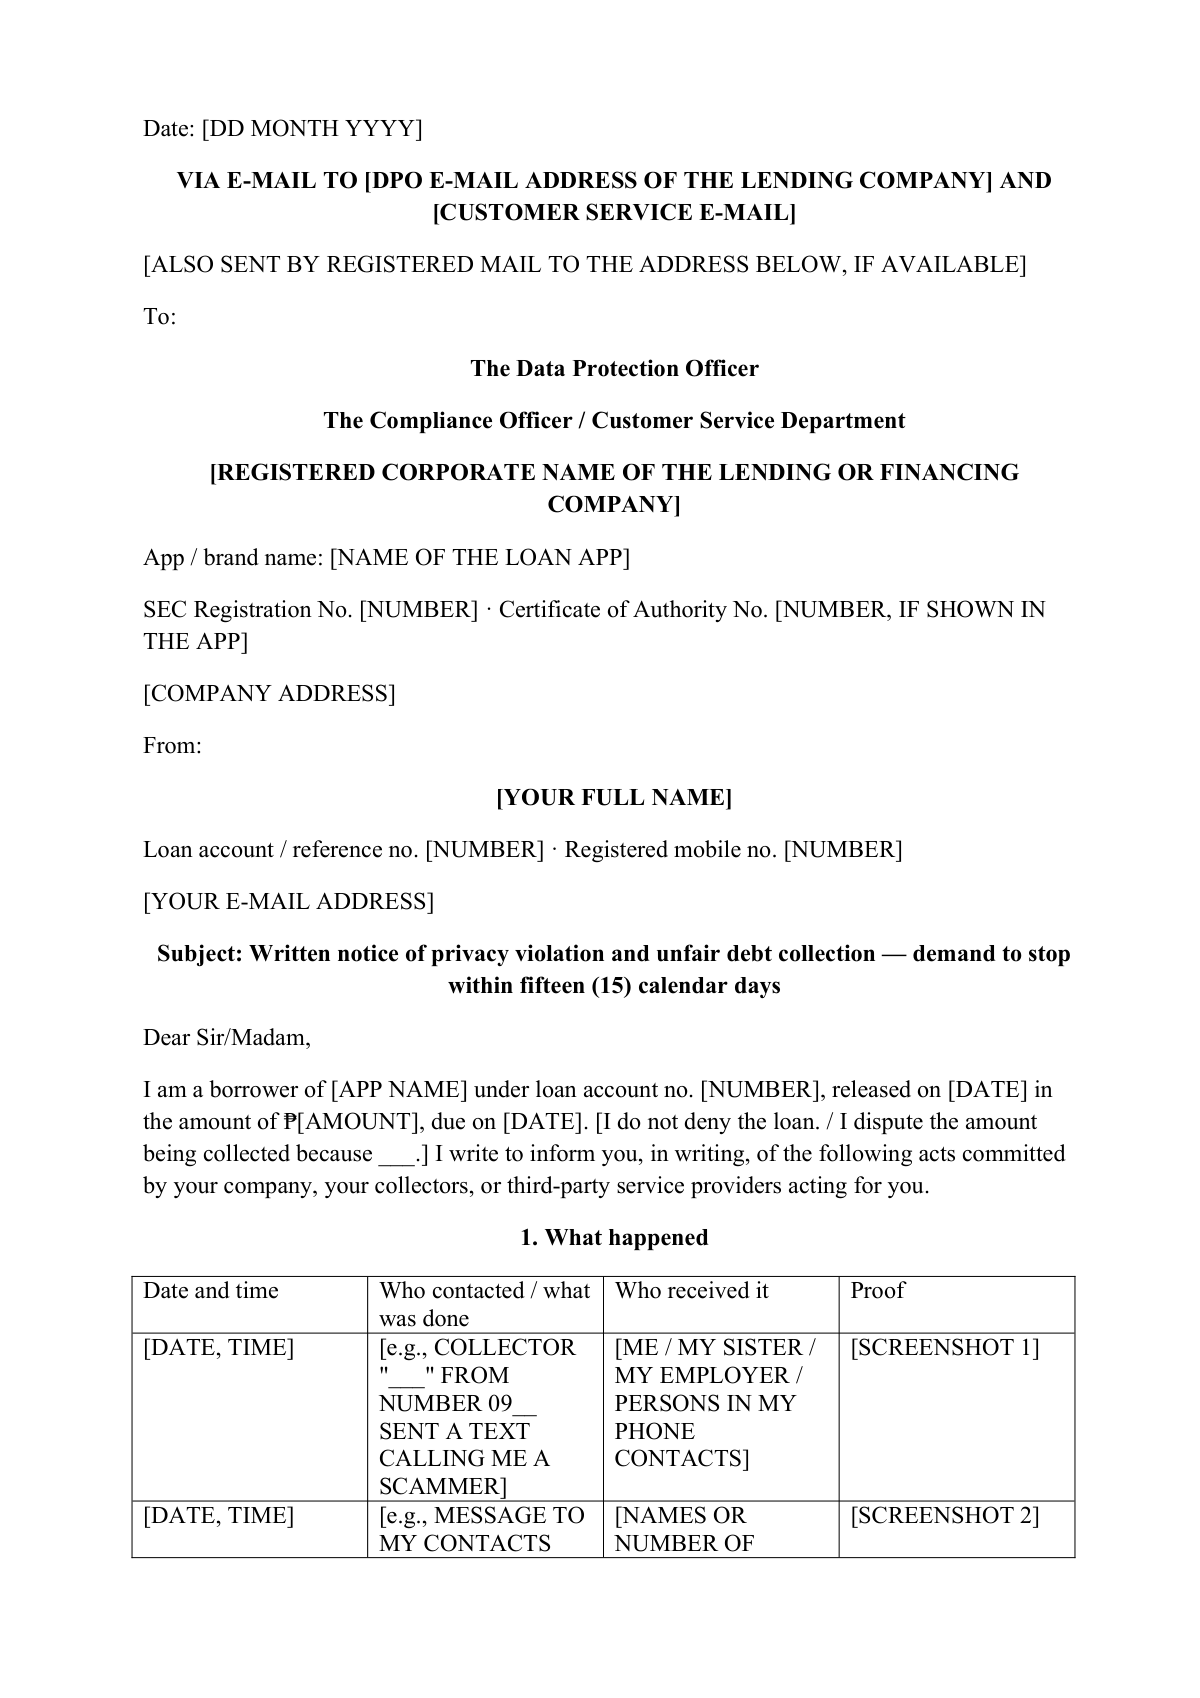
Start typing right in the document — no sign-up. It stays in this browser; save it to your free Layers account to keep it, open it on your phone and share it.
Atty. Liza, Layers template assistant
Before anything else, screenshot every message with the date and the sender's number. Evidence disappears fast.
Send the notice to their Data Protection Officer and write down the day they received it — the 15 days start there.
An illustrated character, not a lawyer.
Deadlines
The rules, with the source
| What | Deadline | Source |
|---|---|---|
| Written notice to the company first | Inform the lender (its DPO) in writing; the NPC acts if there is no appropriate action or no reply within 15 calendar days from receipt | NPC 2021 Rules of Procedure as amended, Rule II, s.2 |
| Waiver of that step | Possible for good cause or serious violations (grave and irreparable damage, no plain or speedy remedy, patently illegal acts) | Rule II, s.2 |
| What the NPC complaint needs | Written, signed and verified; facts and evidence; your correspondence with the company; certification against forum shopping | Rule II, s.3 |
| Prohibited collection practices | Threats, insults, disclosing your name and data, deceptive means, contact before 6 A.M. or after 10 P.M., contacting people in your contacts who are not co-makers or guarantors | SEC Memorandum Circular No. 18, s. 2019, s.1 |
| Collection agencies | The lending company stays responsible for the collectors it hires | SEC MC 18-2019, s.3 |
| Fines for the company | Lending company: ₱25,000 (1st), ₱50,000 (2nd); financing company: ₱50,000 / ₱100,000; 3rd offense up to ₱1 million, suspension or revocation | SEC MC 18-2019, s.5 |
| Your data rights | Be informed, access your data and its recipients, and have unlawfully obtained or misused data blocked or destroyed; damages | Data Privacy Act (R.A. 10173), s.16 |
Contacting people in your contact list who are not your co-makers or guarantors is an unfair collection practice even if you clicked 'allow' when you installed the app (SEC MC 18-2019, s.1(h): 'Notwithstanding the borrower's consent').
Step by step
What to do, in order
1
Save the evidence
Screenshots with date, time and sender; call logs; messages your contacts received.
2
Find the real company
Corporate name, SEC registration and DPO e-mail are in the app's privacy notice or store listing.
3
Fill in the notice
Put each incident in the table. Say what you want them to stop and delete.
4
Send it with proof
E-mail the DPO and customer service; registered mail if there is an address. Note the date received.
5
Wait 15 days
Enter the receipt date above. If they stop and reply properly, keep the reply.
6
File with the NPC and the SEC
Attach the notice, proof of receipt and the evidence. A complaint to one does not stop the other.
Questions
I gave the app access to my contacts. Can they still message them?
SEC MC 18-2019 says contacting people in your contact list other than co-makers or guarantors is an unfair collection practice 'notwithstanding the borrower's consent'.
Do I still have to pay the loan?
Yes, a valid loan stays due. The notice is about how they collect and what they do with your data. Ask for a statement of account so you know the correct amount.
Do I really have to write to them before the NPC?
As a rule, yes: the NPC Rules require written notice and 15 calendar days first. The NPC can waive this for serious cases, for example when the harm is grave and urgent.
Official sources
- NPC Circular No. 2021-01, 2021 Rules of Procedure of the National Privacy Commission, as amended (March 2024) — Rule II, ss.1–3
- SEC Memorandum Circular No. 18, Series of 2019 — Prohibition on Unfair Debt Collection Practices of Financing and Lending Companies
- Data Privacy Act of 2012 (R.A. 10173), s.16 — Lawphil
Other documents
Keep the papers in one place
Letters, receipts and notices in one folder you can share with family or a lawyer. The templates and the editor are free; Layers is free for up to 20 people.
This is a ready document and a deadline calculation, not legal advice.