 Jira & Confluence

 Bitrix24
Banking (Credit Reference Bureau) Regulations, 2020 · Reg. 37
Wrongly listed on CRB? — dispute letter ready, the 21 days counted
Short answer. The dispute letter is already open below: copy the entry from your credit report, tick why it is wrong and send it to the bureau with a copy to the lender. Your right to dispute: In writing, if you believe information in your report is inaccurate, erroneous or outdated (CRB Regulations 2020, reg. 37(5)).
- Bureau must flag the entry as disputed and notify the lender: within 5 working days: type the date
- Bureau must investigate your dispute: within 7 days: type the date
- Earliest end of the lender's 21 days (they run from the day the lender gets the bureau's notice — up to 5 working days later). If not finished, the entry must be deleted: type the date
Working days: Monday to Friday; public holidays are not deducted. Check your own case.
Regulation 37(6)–(8) and (10) of the Banking (Credit Reference Bureau) Regulations, 2020: note on the report and notice to the lender within five working days; the bureau's investigation within seven days of being informed; the lender's investigation within twenty-one days of receiving the bureau's notice of dispute, failing which the disputed information shall be deleted. The Regulations define 'day' as a calendar day. The lender's 21 days start on the day it receives the bureau's notice: if you learn that date, run the calculator again with it. Working days are counted Monday to Friday without public holidays.
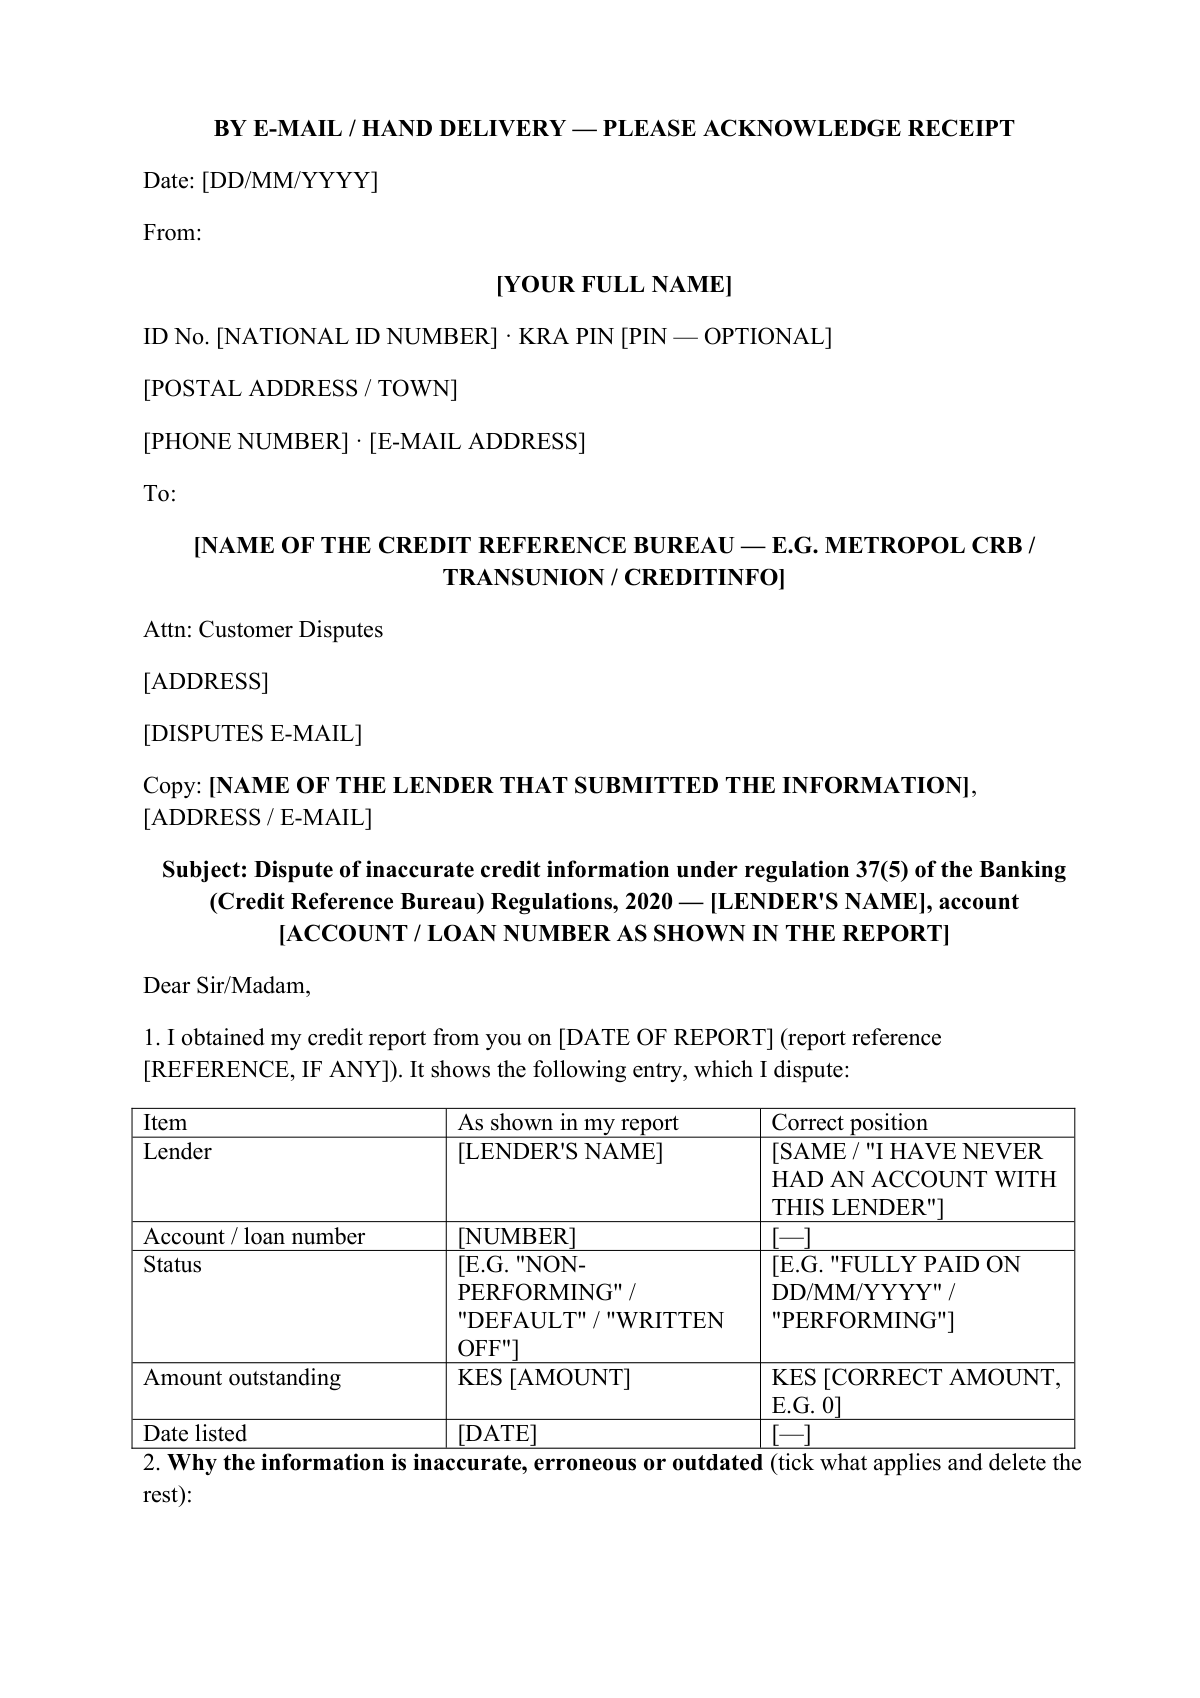
Start typing right in the document — no sign-up. It stays in this browser; save it to your free Layers account to keep it, open it on your phone and share it.
Lida, Layers template assistant
Write down the date the bureau received your dispute — every deadline on this page counts from it.
Attach the proof you have now. A clear payment record or clearance letter is what the lender has to answer in its 21 days.
An illustrated character, not a lawyer.
Deadlines
The rules, with the source
| What | Deadline | Source |
|---|---|---|
| Your right to dispute | In writing, if you believe information in your report is inaccurate, erroneous or outdated | CRB Regulations 2020, reg. 37(5) |
| Note on your report + notice to the lender | Within 5 working days of the dispute | reg. 37(6) |
| Bureau's investigation | Within 7 days of being informed | reg. 37(7) |
| Lender's investigation and notice of resolution | Within 21 days of receiving the bureau's notice | reg. 37(8) |
| Investigation not completed in 21 days | The disputed information must be deleted | reg. 37(10) |
| You still disagree | Statement of up to 100 words added to your report; refer the dispute to the Central Bank of Kenya | reg. 37(13), 37(15) |
| Free credit report | At least once a year from each bureau; given within 5 working days of the request | reg. 37(3)(a), 37(4) |
| Notice before negative listing | At least 30 days before submitting it (credit information provider); one month before the loan becomes non-performing — two weeks if repayments are due at intervals under a month (bank, microfinance bank, Sacco) | reg. 26(1); reg. 63(1)(a) |
| Small amounts | No negative listing where the amount does not exceed KES 1,000 | reg. 18(2) |
| Paid-up defaults | Kept for 5 years from final settlement, then removed | reg. 34(1)(a), 34(3) |
Under the same Regulations a lender must resolve credit information complaints within 30 days of receipt (reg. 63(8)). Digital lenders licensed by the CBK have their own rules on CRB listing in the Non-Deposit Taking Credit Providers Regulations, 2026 (reg. 33): 30 days' notice and no negative listing for KES 1,000 or less.
Step by step
What to do, in order
1
Get your credit report
Request it from each bureau — once a year it is free. Find the wrong entry and note the lender and account number.
2
Fill in the letter
Copy the entry into the table and tick the reason: paid, not your loan, wrong amount, KES 1,000 or less, no notice, or out of date.
3
Attach proof
ID, the report, and proof of payment or a clearance letter. If someone used your identity, add the police OB number.
4
Send it to the bureau, copy the lender
By e-mail or by hand, and ask for an acknowledgement with the date. The deadlines count from that date.
5
Check the result
After the 21 days, request your report again. If the entry is unchanged and the lender did not finish, it should have been deleted.
6
Escalate
Not resolved? Refer the dispute to the Central Bank of Kenya with copies of everything.
Questions
Do I have to pay someone to remove my name from CRB?
No. The dispute is made by you, in writing, to the bureau. A bureau may charge only if the information you disputed turns out to be correct. Nobody can 'clear' a record for a fee.
I paid the loan. Why am I still listed?
A bureau keeps information on a non-performing loan for five years from the date of final settlement. But the entry must show that it is settled — if it still shows an outstanding amount, dispute it with your proof of payment.
What if the lender never answers?
If the lender does not complete its investigation within 21 days of receiving the bureau's notice, the Regulations say the disputed information shall be deleted. Ask the bureau for an updated report to check.
Official sources
Other documents
Keep the papers in one place
Letters, receipts and notices in one folder you can share with family or a lawyer. The templates and the editor are free; Layers is free for up to 20 people.
This is a ready document and a deadline calculation, not legal advice.