 Jira & Confluence

 Bitrix24
FCCPC DEON Regulations 2025 · NDPA 2023
Loan app harassment complaint letter — ready to send, deadlines counted
Short answer. The letter is already open below: add your loan details and the calls and messages, then send it through the app's complaint channel. Complain to the lender first: Required before going to the FCCPC (DEON Consumer Lending Guidelines 2025, para 43; DEON Regulations 2025, reg. 22).
- Lender must give you the statement of your loan account (24 hours, DEON Regulations reg. 21(b)): type the date
- Lender must resolve your complaint (48 hours, DEON Regulations reg. 22(d); Guidelines para 43): type the date
- Outer limit if the lender told you in writing it needs more time — after this, escalate to the FCCPC (Guidelines paras 44–45): type the date
- Lender's decision on your data requests (Notice to Address Grievance, GAID 2025 Schedule 9): type the date
Check your own case.
We count calendar days from the day you send the complaint: 48 hours is shown as 2 days. The Regulations say 24 hours, and never more than 48 hours (reg. 22(d)); the FCCPC Guidelines allow up to 14 days if the lender writes to you explaining why it needs more time (paras 43–44), and provide for escalation to the FCCPC once the 14 days have passed (para 45). The Regulations also let you report violations to the FCCPC (reg. 26) without naming a waiting period. Keep proof of the date and time you sent the letter.
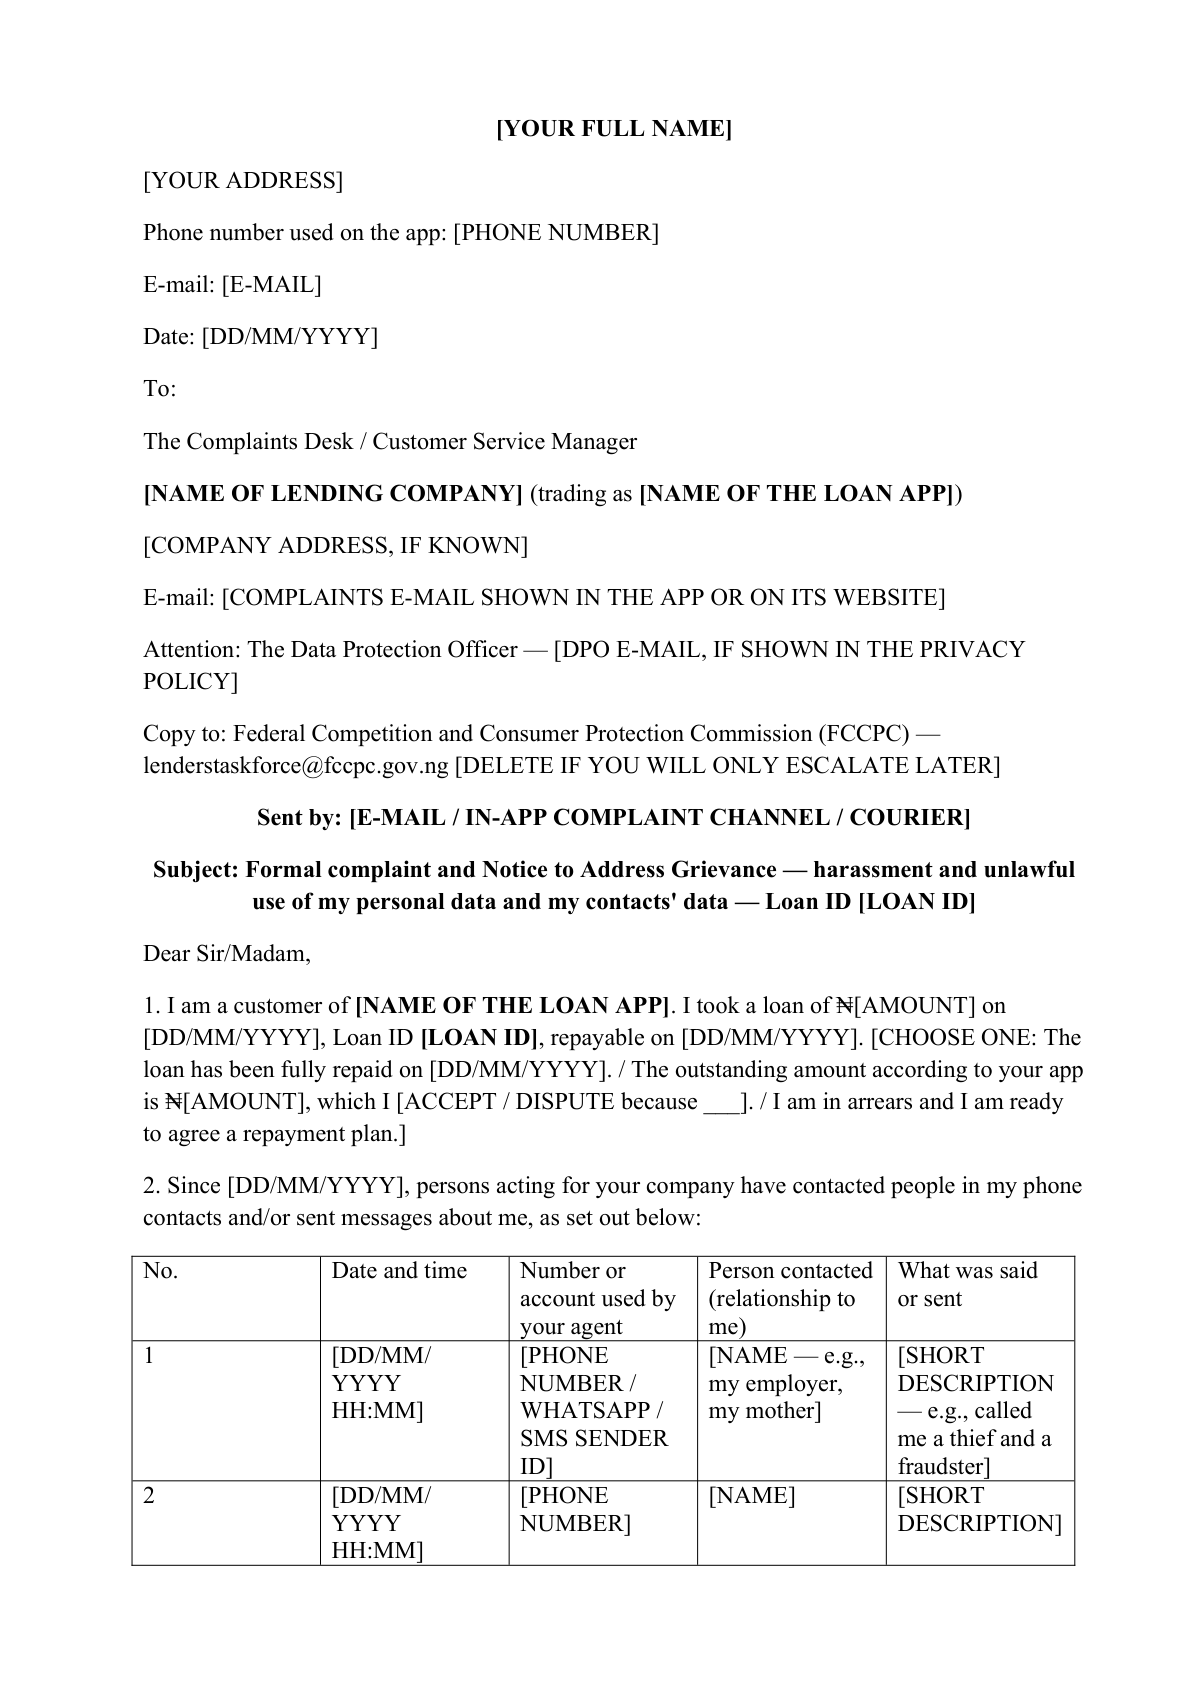
Start typing right in the document — no sign-up. It stays in this browser; save it to your free Layers account to keep it, open it on your phone and share it.
Lida, Layers template assistant
Start with the screenshots — dates and numbers are what the FCCPC will look at. Then send the letter the same day and keep the time you sent it.
Be honest about the loan. A clear offer to pay what you really owe, plus a firm request to stop calling your contacts, reads better than an angry letter.
An illustrated character, not a lawyer.
Deadlines
The rules, with the source
| What | Deadline | Source |
|---|---|---|
| Complain to the lender first | Required before going to the FCCPC | DEON Consumer Lending Guidelines 2025, para 43; DEON Regulations 2025, reg. 22 |
| Lender resolves the complaint | Within 24 hours; where impracticable, never more than 48 hours from receipt | Digital, Electronic, Online, or Non-Traditional Consumer Lending Regulations 2025, reg. 22(d) |
| Complex complaint | Lender must explain in writing and resolve within 14 days of receipt | DEON Consumer Lending Guidelines 2025, para 44 |
| Escalate to the FCCPC | Once 14 days from the lender's receipt have passed, with the lender's replies and your evidence — lenderstaskforce@fccpc.gov.ng | DEON Guidelines 2025, para 45; DEON Regulations 2025, reg. 26(2) |
| Statement of your loan account | Within 24 hours of your demand | DEON Regulations 2025, reg. 21(b) |
| Withdraw consent, object, ask for erasure of your data | Withdrawal at any time; erasure without undue delay | Nigeria Data Protection Act 2023, ss. 34(1)(d), 35, 36 |
| Notice to Address Grievance (data) | Decision within 30 days or the time you set, whichever is earlier; not required before a complaint to the NDPC | NDP Act GAID 2025, Art. 40 and Schedule 9 |
| Penalty for a lender breaking the Regulations | Up to ₦100 million or 1% of turnover (company); suspension or delisting | DEON Regulations 2025, reg. 27 |
The DEON Regulations cover digital lenders registered with the FCCPC. They do not cover banks and microfinance banks licensed under BOFIA — if your app belongs to one, complain to the bank and then to the CBN (cpd@cbn.gov.ng). Data protection rights apply to every lender.
Step by step
What to do, in order
1
Save the evidence
Screenshot every message and call log before you block anyone: date, time, number, what was said.
2
Check the lender
Look for the app on the FCCPC list of approved digital lenders. Not on the list? Say so in your letter.
3
Fill in and send the letter
Use the complaint channel in the app and e-mail. Note the date and time you sent it.
4
Ask for a reference number
The lender should resolve it in 48 hours, or tell you in writing why it needs more time.
5
Escalate to the FCCPC
No fix within 14 days? Send the letter, the lender's replies and your screenshots to lenderstaskforce@fccpc.gov.ng or complaints.fccpc.gov.ng.
6
Complain about your data
If the lender keeps using your contacts, lodge a complaint with the Nigeria Data Protection Commission as well.
Questions
Is it legal for a loan app to call my contacts?
Lenders registering with the FCCPC must confirm their apps will not access customers' contacts, call logs and photos, and must follow the data protection law. Your contacts never agreed to be called about your loan. You can withdraw consent and demand erasure of that data.
I still owe money. Can I complain?
Yes. Owing money does not allow anyone to shame you or call your family and employer. Say honestly what you owe and offer a payment plan — that makes your complaint stronger.
The lender did not reply. What next?
The FCCPC Guidelines provide for escalation once 14 days have passed since the lender received your complaint; the Regulations also let you report violations to the FCCPC (reg. 26). Send your letter and evidence to lenderstaskforce@fccpc.gov.ng. You can complain to the Nigeria Data Protection Commission too — the Notice to Address Grievance is not a condition for that.
Official sources
- Digital, Electronic, Online, or Non-Traditional Consumer Lending Regulations 2025 (FCCPC)
- DEON Consumer Lending Guidelines 2025 (FCCPC), paras 42–47
- Nigeria Data Protection Act 2023, ss. 34–36, 46 (NDPC)
- NDP Act General Application and Implementation Directive (GAID) 2025, Arts. 38–40, Schedule 9
- FCCPC complaints portal
Other documents
Keep the papers in one place
Letters, receipts and notices in one folder you can share with family or a lawyer. The templates and the editor are free; Layers is free for up to 20 people.
This is a ready document and a deadline calculation, not legal advice.