 Jira & Confluence

 Bitrix24
Prescription Act · National Credit Act s.126B
Collector chasing a debt older than 3 years? — prescribed debt letter, ready to send
Short answer. The letter is already open below: fill in the account details and send it in writing. Most debts: store cards, personal loans, credit cards, accounts: Prescribe after 3 years (Prescription Act 68 of 1969, s.11(d)).
- Earliest date the debt prescribes (3 years), if nothing interrupted it after this date: type the date
Check your own case.
Three years under s.11(d) of the Prescription Act 68 of 1969, counted from when the debt became due (s.12(1)) and running afresh from any acknowledgement of the debt (s.14). A summons served on you also interrupts it (s.15). Home loans, judgment debts and tax take 30 years (s.11(a)) — this count does not apply to them. If you challenge a credit bureau listing, the bureau has 20 business days from your challenge (National Credit Act s.72(3), regulation 20(2)).
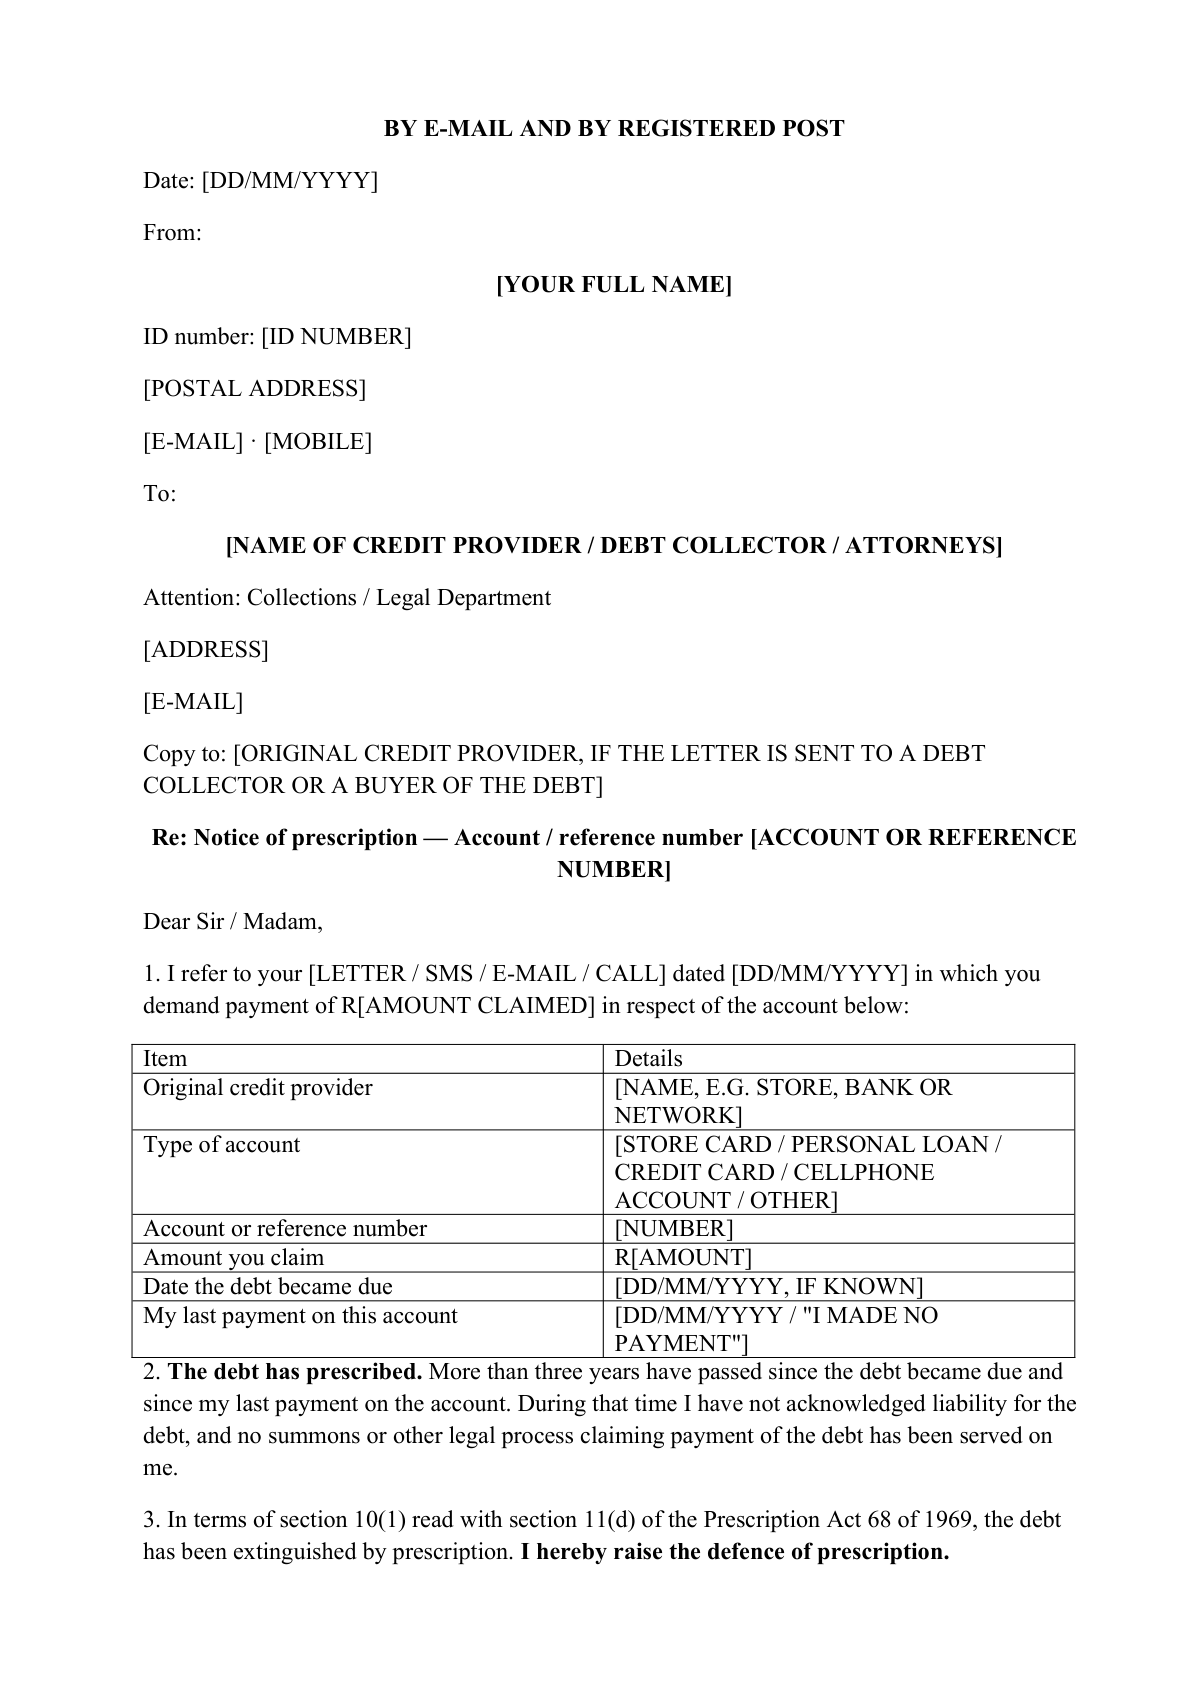
Start typing right in the document — no sign-up. It stays in this browser; save it to your free Layers account to keep it, open it on your phone and share it.
Lida, Layers template assistant
Give me the date of your last payment on the account and I will show you when the three years end. Until then, don't pay and don't sign anything the collector sends.
Send the letter in writing and keep proof of delivery. On the phone, don't say 'I owe' — just ask them to reply in writing.
An illustrated character, not a lawyer.
Deadlines
The rules, with the source
| What | Deadline | Source |
|---|---|---|
| Most debts: store cards, personal loans, credit cards, accounts | Prescribe after 3 years | Prescription Act 68 of 1969, s.11(d) |
| Home loan (mortgage bond), judgment debt, tax | 30 years | s.11(a) |
| Cheque or other negotiable instrument, notarial contract | 6 years | s.11(c) |
| When the clock starts | As soon as the debt is due | s.12(1) |
| Acknowledging the debt (expressly or tacitly) | Interrupts prescription; the period starts again from that day | s.14 |
| Summons served on you | Interrupts prescription | s.15(1) |
| Who raises prescription | You must: a court will not take notice of it on its own | s.17(1) |
| Credit agreements under the NCA | No sale of a prescribed debt; no further collection once you raise prescription | National Credit Act 34 of 2005, s.126B |
| Credit bureau listing of a prescribed debt | May not be submitted to a credit bureau | National Credit Regulations 2006, reg. 19(5) |
| Challenging a credit bureau listing | Bureau or credit provider must act within 20 business days | NCA s.72(3); reg. 20(2) |
Paying a prescribed debt still counts as a valid payment (Prescription Act s.10(3)), so you cannot claim it back. Section 126B applies to debts under credit agreements covered by the National Credit Act.
Step by step
What to do, in order
1
Find your last payment
Check old statements or your credit report for the last payment date on the account.
2
Count the three years
Enter that date. If three years have passed with no acknowledgement and no summons, the debt may have prescribed.
3
Don't pay, don't promise
A payment or a written promise to pay can restart the clock. Stay in writing.
4
Fill in and send the letter
By e-mail and registered post to the collector, with a copy to the original creditor.
5
Clean up your credit report
Dispute the listing with the credit bureau: it has 20 business days to act.
6
If collection continues
Lodge a complaint with the National Credit Regulator and keep every message as evidence.
Questions
Does the debt just disappear after three years?
Only if nothing interrupted the three years: no acknowledgement of the debt and no summons served on you. And you have to raise prescription yourself — the court will not do it for you.
I paid R50 last year. Has the clock restarted?
It may have. An acknowledgement of the debt, express or tacit, restarts prescription, and a payment can be treated as one. Enter the date of that payment in the calculator and get advice if the amount is large.
Does this work for a home loan or SARS?
No. A debt secured by a mortgage bond, a judgment debt and tax prescribe after 30 years, not three.
Official sources
Other documents
Keep the papers in one place
Letters, receipts and notices in one folder you can share with family or a lawyer. The templates and the editor are free; Layers is free for up to 20 people.
This is a ready document and a deadline calculation, not legal advice.