 Jira & Confluence

 Bitrix24
BIR Form 2316 · request · January 31
BIR Form 2316 request letter — due January 31, or on your final pay day if you left
Ready, not blank.
Fill it in and download it in Word for free.
Short answer. Your employer gives your Form 2316 by January 31 — or on the day of your last pay if you resigned. Still employed: form 2316 on or before January 31 of the following year (RR 2-98, Sec. 2.83.1, as amended by RR 11-2018).
Enter a date — we’ll count the deadlines
- Form 2316 due from your employertype the date
- Reply date to write in your letter (suggested: 5 working days)type the date
Layers never asks for a code or payment in a message.
Working days: Monday to Friday; public holidays are not deducted. Check your own case.
RR No. 2-98, Sec. 2.83.1, as amended by RR No. 11-2018: Form 2316 is furnished on or before January 31 of the following year, or — if employment ends before the year closes — on the day the last payment of compensation is made. The 5 working days are a suggestion for your letter, not a legal period.
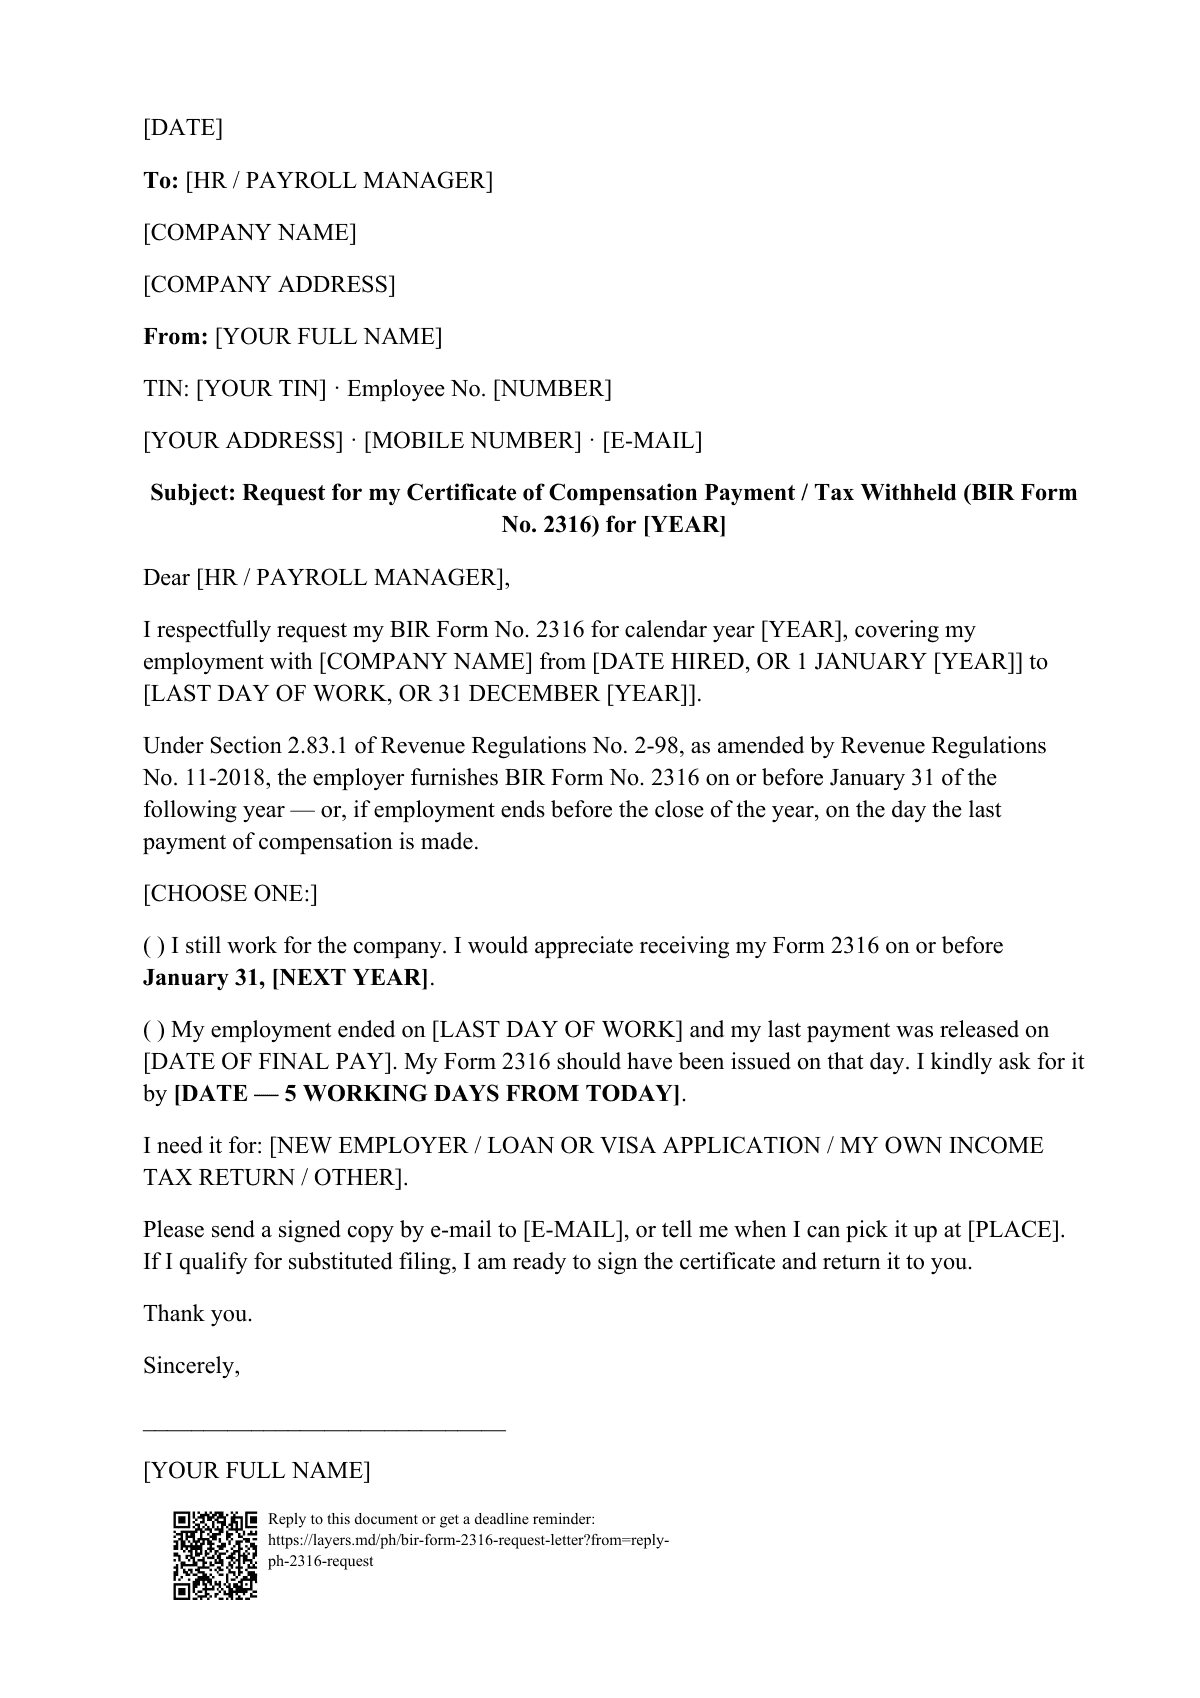
We will ask you to confirm this address, then email you the recipient’s reply.
Start typing right in the document — no sign-up. It stays in this browser; save it to your free Layers account to keep it, open it on your phone and share it.
Liza, Layers template assistant
Tell me the day your final pay was released, and I will show you when your Form 2316 was due.
If it is late, the follow-up letter is already written — just add your name and TIN.
Deadlines
The rules, with the source
| What | Deadline | Source |
|---|---|---|
| Still employed | Form 2316 on or before January 31 of the following year | RR 2-98, Sec. 2.83.1, as amended by RR 11-2018 |
| Left before the year ended | on the day the last payment of compensation is made | RR 2-98, Sec. 2.83.1, as amended by RR 11-2018 |
| New job in the same year | give your new employer the 2316 from your previous employer | RR 2-98, Sec. 2.83.1, as amended by RR 11-2018 |
| Substituted filing | sign the 2316 and return it to your employer; the employer files the list with the BIR by February 28 | RR 2-98, Sec. 2.83.1, as amended by RR 11-2018 |
| No substituted filing | the 2316 is part of your income tax return, filed on or before April 15 | RR 2-98, Sec. 2.83.1, as amended by RR 11-2018 |
| If the employer does not give it | a ground for mandatory audit of the employer upon verified complaint | RR 2-98, Sec. 2.83.1, as amended by RR 11-2018 |
Quoted from Revenue Regulations No. 11-2018 (Section 2.83.1). The BIR has moved some year-end deadlines before; check bir.gov.ph for an advisory for this year.
Step by step
What to do, in order
1
Write the request
E-mail to HR or payroll is enough; the letter below is ready.
2
Say why you need it
New employer, loan, visa or your own return — HR often prioritizes by purpose.
3
Keep the sent copy
The date you asked matters if you need to follow up.
4
Sign if you qualify for substituted filing
Sign the certificate and give it back; your employer signs and files the list.
5
Follow up
The follow-up letter is on the second page.
6
Still nothing
Ask your Revenue District Office (RDO) of the BIR for assistance.
Questions
When must my employer give my Form 2316?
On or before January 31 of the following year. If you left during the year, on the day your last pay is released (RR 2-98, Sec. 2.83.1, as amended by RR 11-2018).
I changed jobs this year. Do I need the 2316 from my old employer?
Yes. The regulation asks you to give your new employer the 2316 from your previous employer, so the year's tax is computed on all your compensation.
My employer will not release it. What can I do?
Send this letter and the follow-up. The regulation makes failure to furnish the 2316 a ground for a mandatory audit of the employer upon verified complaint — ask your BIR Revenue District Office how to file one.
Official sources
Other documents
Keep the papers in one place
Letters, receipts and notices in one folder you can share with family or a lawyer. The templates and the editor are free; Layers is free for up to 20 people.
This is a ready letter and a date calculation, not legal or tax advice.