 Jira & Confluence

 Bitrix24
529 plan · college savings · by age
529 college savings calculator — how much to save each month for your child's college
Short answer. Put in your child's age, a year of college at today's prices, how many years and how much of it you want to cover, plus your savings and expected return: you see the goal when college starts and the monthly amount to get there. Tax-free growth: 529 earnings grow federally tax-free; withdrawals for qualified education expenses are tax-free (IRS Publication 970).
- Review the plan and raise the monthly amounttype the date
- Share the gift link before the holidaystype the date
Check your own case.
A yearly review reminder, not a deadline.
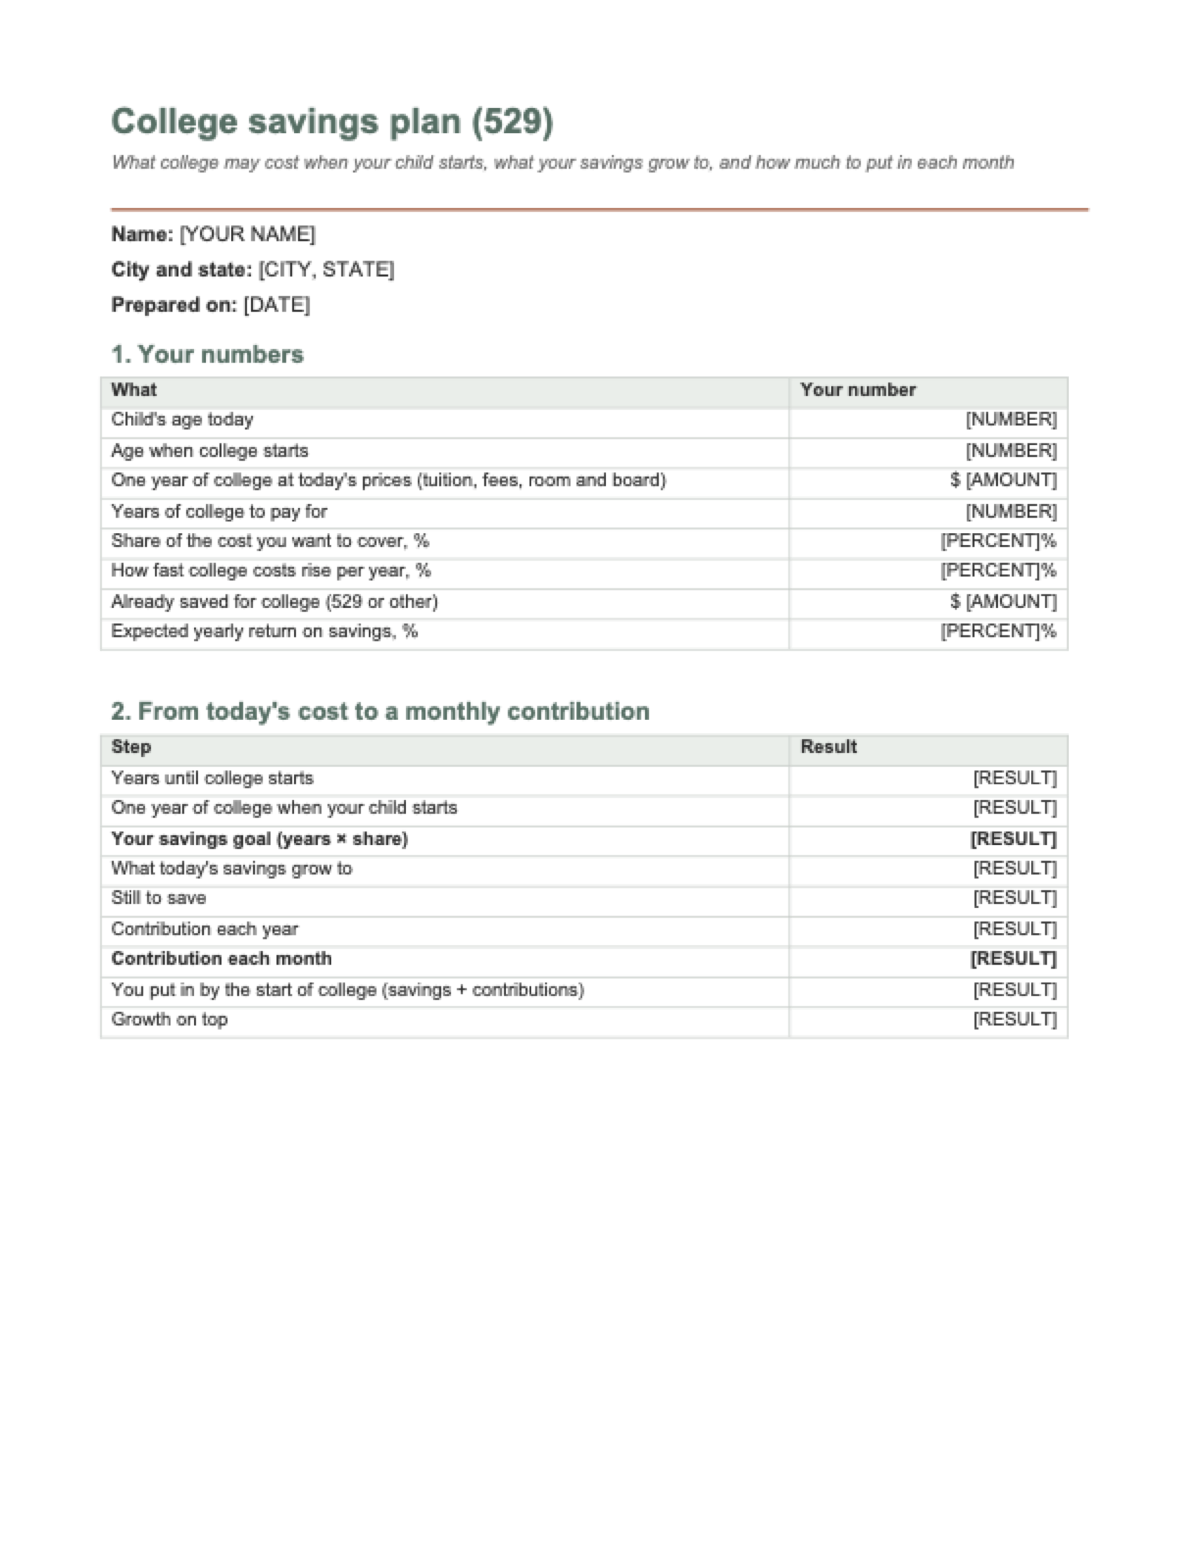
Start typing right in the document — no sign-up. It stays in this browser; save it to your free Layers account to keep it, open it on your phone and share it.
529 plan · college savings · by age
Your college savings goal — and the monthly amount to reach it
Put in your child's age, a year of college at today's prices, how many years and how much of it you want to cover, plus your savings and expected return: you see the goal when college starts and the monthly amount to get there. No sign-up.
- Compare your state's 529 plan — many states give a tax break.
- Set up an automatic monthly contribution.
- Share the gift link with grandparents before birthdays and holidays.
Arithmetic only, with your assumptions: cost grows by your inflation rate each year until college; savings grow by your expected return, compounded yearly; contributions at the end of each year. Every year of college is priced at the first year's cost. Not investment advice: returns are not guaranteed.
Lida, Layers template assistant
Tell me your child's age and the college you have in mind, and I will show the monthly amount to save.
The Excel file shows the balance birthday by birthday.
Deadlines
The rules, with the source
| What | Deadline | Source |
|---|---|---|
| Tax-free growth | 529 earnings grow federally tax-free; withdrawals for qualified education expenses are tax-free | IRS Publication 970 |
| Qualified expenses | Tuition, required fees, books, supplies, equipment; room and board for students enrolled at least half-time | IRS Publication 970 |
| Non-qualified withdrawals | Earnings are taxable and usually get a 10% additional tax | IRS Publication 970 |
| Gifts | 2026 annual gift exclusion: $19,000 per giver per child | IRS IR-2025-103 |
The return and the college inflation rate are your assumptions, not predictions; investments can lose value. Many states give a tax break for their own plan — check your state's 529.
Step by step
What to do, in order
1
Pick the college
One year at today's prices and the number of years.
2
Add what you have
Savings now and the return you assume.
3
See the monthly amount
Goal, growth and a year-by-year table.
Questions
How much should I save for college each month?
It depends on the cost, the years left and the return. The calculator grows today's cost to the first year of college, subtracts what your savings will grow to, and spreads the rest over the years left.
How much should be in a 529 by age?
Put in your child's age: the year-by-year sheet shows the balance you need each birthday to stay on track.
What can a 529 pay for?
Qualified education expenses — tuition, fees, books, supplies, equipment and, for students enrolled at least half-time, room and board within the school's cost of attendance (IRS Publication 970).
Can grandparents contribute?
Yes. In 2026 each person can give up to $19,000 to each child without using their lifetime exemption, and 529 gifts can be spread over five years for gift-tax purposes.
Is it free? Do I need to sign up?
It is free and you do not need to sign up: fill in, see the result and download the files. With a free account you can save a copy to your Layers.
Official sources
Other documents
Keep the papers in one place
Letters, receipts and notices in one folder you can share with family or a lawyer. The templates and the editor are free; Layers is free for up to 20 people.
A savings plan, not investment or tax advice. Returns are not guaranteed.